
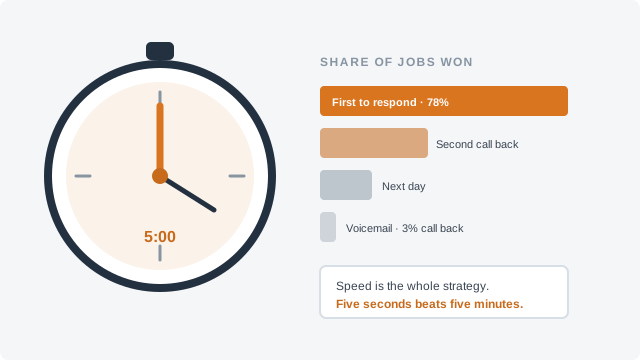
Say a hailstorm crosses your county on a Tuesday afternoon. By Thursday you have two hundred calls, texts and form fills, and they keep coming. Some of those people have water running down a bedroom wall. Some have a dented gutter. Some saw a roofing truck at the neighbor’s and want to know if they should worry. Answer them in the order they arrived and the leak waits behind the gutter.
This is a plan for the first two weeks: answer everyone, sort by safety and active damage, check where the storm actually hit, give honest dates, and stay inside the rules that come into play after a storm.
First, one honest answer for everyone
Before you sort anything, everyone who got in touch needs to know you have their message and what happens next. One short reply, the same for all, does it: you got their message, here is roughly when you expect to be in touch again or visit, and if water is coming inside right now, they should say so in their reply and they move to the front. That last line does half your triage for you.
Keep the dates honest. The FTC’s advice to homeowners after weather emergencies says: “Be skeptical of anyone promising immediate clean-up or repairs.” It also lists, among the signs of a scam: “Scammers say you’ll get a discount, but only if you sign a contract right away.” A reply that promises tomorrow when you cannot deliver it, or a storm discount that expires Friday, puts you in the same sentence as the people the FTC is warning about. If your first open slot is three weeks out, say three weeks. Busy Season: Honest Lead Times and a Waitlist covers how to give real lead times and keep a waitlist moving.
Sort by safety and active damage
Ask every caller the same questions in the same order, and write the answers down:
- Is water coming inside the house right now?
- Is anything resting on the roof or the house: a tree, a limb, debris?
- Are any power lines down on or near the property?
- What is the address? (Is it in your area at all?)
- Has a claim been filed, and has an adjuster been out or been scheduled?
- Can they send photos of what they can see safely from the ground?
Photos let you sort without driving; Ask for Photos Before You Drive Out covers what to ask for. Then each lead goes in one of four piles.
| Pile | What it means | What you do |
|---|---|---|
| 1. Today | Water coming in, an opening in the roof or a wall, something resting on the structure | Temporary protection as soon as it is safe to send a crew |
| 2. This week | Visible damage, no active leak | An inspection visit, in the order they called |
| 3. Scheduled | No visible damage; checking because of the storm | A photo review, or an inspection slot after piles 1 and 2 |
| 4. Not yours | Outside your area or your trade | Refer or decline the same day |
Pile 4 deserves the same day’s attention as pile 1, because a fast “we can’t, try someone else” frees the homeowner to find help. Leads Outside Your Service Area covers how to refer or decline well.
Downed lines are not a roofing problem. OSHA’s fact sheet on roof tarping tells employers to look for downed overhead power lines and “treat all power lines as ‘live’,” and to contact the utility company to make sure lines are de-energized. Tell the homeowner to report the line to the utility, and send no crew until it is dealt with.
Check where the storm actually hit
When the calls come from all over, it helps to know where the hail actually fell. Two free NOAA sources answer that question at very different speeds.
Use the first to plan this week’s routes and the second months later, when a file needs the official date and size of the event. Neither says anything about one particular roof. A hail report two towns over is not damage on this house, and telling a homeowner otherwise is how storm selling earned its reputation.
Temporary repairs come first
For pile 1, this week’s job is protection, not the replacement. The homeowner’s insurer expects it. The NAIC’s consumer guide to home insurance says that when filing a claim, “You’re also required to protect your home from further damage,” with boarding up as its example. The Texas Department of Insurance’s home insurance guide is more specific: “Make only temporary repairs to protect your house and belongings. For instance, board up broken windows or put a tarp over a damaged roof. Don’t make permanent repairs.” It warns that the insurer “might deny your claim if you make permanent repairs before it sees the damage,” and tells homeowners to keep receipts for materials bought for repairs.
So a pile-1 visit is a tarp or a board-up, photos before and after, and an itemized receipt the homeowner can hand to the insurer. The full estimate follows once the adjuster has seen the damage. TDI also suggests having the contractor there for the adjuster’s visit, because “Your contractor can talk to the adjuster about estimates and other issues.” Where talking about your estimate ends and adjusting the claim begins is a state-law line; Roofers and Insurance Claims shows where four states draw it.
Tarping without a fall
Storm tarping is rushed work on damaged roofs, often wet ones. OSHA’s Roof Tarping (Blue Roof) Safety fact sheet lists the steps. Among them:
Fall Protection: OSHA’s Most-Cited Rule covers the six-foot line in full.
Work to what homeowners are being told
This is what the FTC tells homeowners to watch for after a weather emergency. Some of its lines:
Build your process so every one of those works in your favor. Send your license number and certificate of insurance with the first estimate. Put every job on a written contract with dates and a payment schedule. Ask for a deposit your state allows (How Big a Deposit Can You Legally Ask For?), not the full price. Leave coverage questions to the insurer. And when the insurance check names the homeowner and the mortgage company, work with the staged release instead of asking for the check; Insurance Checks Made Out to the Homeowner and the Mortgage Company explains how that money moves.
The rules that come into play after a storm
Keep one log
Two hundred leads will not fit in your head or your phone’s call history. One sheet, one row per lead, with these columns:
| Column | Why it is there |
|---|---|
| Date and time of first contact | Shows who has waited longest in each pile |
| Name, address, county | Your service area, and a match against the storm reports |
| Pile (1 to 4) | Sets the day’s order |
| Water inside? Lines down? | Safety first, every time the sheet is sorted |
| Claim filed? Adjuster date? | Plan the visit around the adjuster |
| Photos received | Sort without driving |
| Next step and the date you gave | So the promise gets kept |
| Outcome | Won, lost, referred or declined |
Give a date only from this sheet, and when a date slips, tell the homeowner before it passes, not after. If you are a roofer, the roofing page covers the first days after a hailstorm and why it pays to ask “is this an insurance claim?” before you call back.
General information, not legal or tax advice. Rules change and vary by state; check with the agency named above or a professional for your situation.