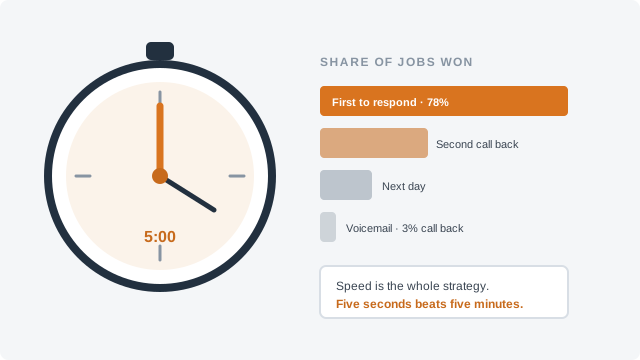
“How do I show a customer I’m legit?” The question often arrives in five words, by text or email: “Are you licensed and insured?” The quickest answer is “Yes,” and it is the weakest, because anyone can type it. The homeowner asking has very likely been told to check, and she will trust what she can check herself. So answer with things she can check, in one message, the same day she asks.
What homeowners are told to check
The advice homeowners read is consistent, and it tells you exactly what your answer needs to hold.
Put together, she wants four things: a license she can look up, a current certificate, a straight answer on workers’ comp, and the same for anyone else who will work on her house.
The one-message answer
Say a painter in Sacramento gets an email from a new lead: “Are you licensed and insured?” Here is a reply that answers all four checks at once. The brackets are yours to fill in.
“Yes. Our California contractor license is [number], issued to [exact business name]. You can look it up on the Contractors State License Board’s Check a License page; it shows the license status and our workers’ compensation information. I’ve attached a current certificate of insurance for our general liability and workers’ compensation policies, with you named as the certificate holder. If any part of your job goes to a subcontractor, you’ll get the same proof for them before they start. [Owner’s name], [Business name]”
Send it as an email with the certificate attached, or as a text with the license number and a note that the certificate is in her inbox. Each line is there for a reason.
The license line
Give the number, the exact business name the license was issued to, and the name of the state’s lookup page. The name matters: if your truck says one name and the license another, she will notice when she searches. Use the agency’s own word, too; if your state registers home improvement contractors rather than licensing them, say registered. If you hold more than one credential, a state trade license and a local license for example, list each one.
State agencies point homeowners to these lookups by name. Virginia’s Statement of Consumer Protections, for one, tells consumers to verify that a contractor is properly licensed before signing, points them to the “License Lookup” feature on the department’s website, and says the license number “should be included in a contract.” Pointing her to the page she has been told to use saves her the hunt. If you are not sure which agency licenses your work, Do I Need a Contractor License? shows how to find it.
Before you send anyone there, look yourself up the way she will. Check that the status is active, that the name and address match what you use, and that the classification covers the job she asked about. In California the board says contractors must have their license number on their business card and on all bids and contracts, so the number in your reply should match the one on everything else she sees.
The certificate
A certificate of insurance is a short summary your agent issues that lists your insurer, the policies you carry and their dates. Ask your agent for one with the homeowner named as certificate holder, and ask how to get them quickly; a homeowner who asks on Saturday is still deciding on Saturday.
Know what the paper is and is not. Oregon’s insurance regulator puts it plainly: certificates “are not the same as an insurance policy. They are issued for information only; they do not amend, extend, or change coverage.” It adds that a certificate states only that the insurer will deliver notice of cancellation “in accordance with policy provisions.” So do not describe the certificate as more than it is. If a customer or a property manager wants to be covered by your policy as an additional insured, that takes an endorsement on the policy, not a name on a certificate; Contractor Insurance explains the difference.
The FTC tells homeowners to make sure certificates are current, so check the dates before you send one. If your policy renews in the middle of her job, send the new certificate when it does.
Workers’ comp: the honest answer either way
This is the line with the most at stake for her. California’s board explains it to them directly: if a worker is injured on the property and the contractor does not have insurance, “you could be financially liable to pay for injuries and rehabilitation.”
If you have employees, your state very likely requires coverage, and the rules differ by state. California requires it “even if they have only one employee,” and requires all active C-8 concrete, C-20 HVAC, C-22 asbestos abatement, C-39 roofing and C-61/D-49 tree service contractors to carry it, or hold a valid certification of self-insurance, whether or not they have employees. Florida requires construction employers with one or more employees to carry it, counting owners who are corporate officers or LLC members.
If you work alone and carry no comp, say so, and show the state’s paper if there is one. In California, a contractor with no employees and none of the classifications above can file an exemption from workers’ compensation with the board, and the license lookup shows the board’s workers’ comp information. In Florida, an officer or LLC member who owns at least 10 percent may elect to be exempt, no more than three officers or members per company or group of affiliated companies, and the Division of Workers’ Compensation runs an exemption search and a Proof of Coverage database a homeowner can search by employer name. An exemption is not insurance, so never call it coverage; and avoid “fully insured” on its own, since it can be read as more than you carry.
Answer it before anyone asks
The fastest reply is the one she never has to request. Put the same proof where she will meet it first:
When part of the job is not yours to prove
Sometimes the honest answer is “not for that part.” If her job includes work your license does not cover, the electrical in a remodel for example, say who will do it and send that company’s license and certificate too. The FTC tells her to check subcontractors’ insurance and licenses, so she will ask eventually. Never lend or borrow a license to close the gap: Virginia, for one, makes “presenting or attempting to use the license or certificate of another” a Class 1 misdemeanor (Va. Code §54.1-1115). For collecting your subs’ proof before their first day, see Uninsured Subcontractors.
Set it up this week
- Look yourself up on your state’s license search, as a homeowner would. Fix any name, address or status problem first.
- Ask your agent for a current certificate and the fastest way to get one with a new certificate holder’s name on it.
- Write down your workers’ comp answer: the policy, or the exemption and where it shows.
- Save the reply above as a template, filled in, on your phone and in your email.
- Add the license line and the certificate offer to your website and your estimate.
- Put a reminder on your calendar for each renewal date, so nothing you send is out of date.
A homeowner who gets a number she can look up, a certificate with her name on it and a straight answer on comp, all before she has to ask twice, has learned something about how you will run her job.
General information, not legal or tax advice. Rules change and vary by state; check with the agency named above or a professional for your situation.